Key Takeaways
- Form EA must reach employees by 28 February 2026, Form E by 31 March 2026, with an extension until 30 April 2026 available for e-Filing.
- Individuals file Form BE by 30 April 2026 and Form B by 30 June 2026, with a 15-day e-Filing grace on each.
- Companies file Form C within 7 months of financial year end, or 8 months via e-Filing.
- CP204 is due at least 30 days before a new basis period, with CP204A revision windows in months 6, 9, and 11.
- MITRS documents are due within 30 days after your Form C e-Filing date.
What are Malaysia's 2026 tax filing deadlines?
The Malaysia tax filing deadline 2026 is a set of staggered LHDN cut-offs across the year. Individuals without business income file Form BE by 30 April 2026 (e-Filing 15 May). Individuals with business income file Form B by 30 June 2026 (e-Filing 15 July). Companies file Form C within 7 months of financial year end, or 8 months via e-Filing.
If you run a Sdn Bhd, the deadlines you really care about stretch across the whole year because you will juggle employer returns, monthly CP204 instalments, the annual tax estimate cycle, and annual tax return Form C. This guide walks through each deadline, its statutory basis, and the exact month it lands in so you can plug dates straight into your finance calendar. First-time directors who need broader context on their duties will find our Sdn Bhd director tax obligations pillar guide a useful companion read.
2026 deadlines by form type and taxpayer
This section is the core reference. Use it as your master list for 2026 planning, then cross-check each item against the LHDN 2026 Return Form Filing Programme before you file.
Employer returns and Form EA
Form EA is the annual statement of remuneration that every employer must give each employee by 28 February 2026. It is the document your staff need to file their own Form BE or Form B.
Form E is the employer's annual return. The submission is due by 31 March 2026, with an e-Filing grace period to 30 April 2026. Form E applies to all employers, including dormant companies and employers without employees. Form C.P.8D (the attachment to Form E) is mandatory to declare the detailed remuneration for every employee. Employers which are Sole Proprietorship, Partnership, Hindu Joint Family and Deceased Person’s Estate who do not have employees are exempted from submitting C.P.8D.
Individual income tax forms
- Form BE (resident individual, no business income): 30 April 2026 (statutory deadline), 15 May 2026 via e-Filing.
- Form M and Form MT (non-resident individual, no business income): 30 April 2026 (statutory deadline), 15 May 2026 via e-Filing.
- Form BT (resident knowledge worker or expert, no business income): 30 April 2026 (statutory deadline), 15 May 2026 via e-Filing.
- Form BT (resident knowledge worker or expert with business income): 30 June 2026 (statutory deadline), 15 July 2026 via e-Filing.
- Form B (individual with business income): 30 June 2026 (statutory deadline), 15 July 2026 via e-Filing.
Company and LLP returns
- Form C (company, Sdn Bhd): 7 months after financial year end (statutory deadline), 8 months after financial year end via e-Filing. Worked example: if your company financial year end is 31 December 2025, Form C is due 31 August 2026 via e-Filing.
- Form PT (LLP): 7 months after financial year end (statutory deadline), 8 months after financial year end via e-Filing.
Partnership and special entities
- Form P (partnership): 30 June 2026 (statutory deadline), 15 July 2026 via e-Filing.
- Form TA (trust bodies), Form TR (REITs), Form TN (business trusts): 7 months after financial year end (statutory deadline), 8 months after financial year end via e-Filing.
Each form is tied to a specific taxpayer category, and mixing them up is one of the most common filing errors. Our breakdown of Form B, Form C, and Form E explains which form each entity type needs, and when.

CP204 tax estimate schedule for Sdn Bhd
CP204 is the annual tax estimate every company and LLP must file with LHDN under section 107C of the Income Tax Act 1967. Late or under-estimated CP204 submissions are the single biggest source of avoidable surcharges for Malaysian SMEs, so pay close attention to the four moving parts below. A deeper walkthrough sits in our CP204 tax estimate Malaysia guide.
New Sdn Bhd first CP204
A newly incorporated company with a first basis period of at least six months must submit CP204 within three months from commencement of operations. If your first basis period is less than six months, you are not required to submit CP204 for that short period, but you must still file Form C.
Existing companies
For existing companies, CP204 must be submitted at least 30 days before the new basis period begins. The estimate must be at least 85 percent of the prior year's revised estimate, or the original estimate if no revision was filed. Under-estimation of more than 30 percent from the revised or original estimate triggers a 10 percent surcharge on the shortfall under section 107C(10).
Monthly instalment due dates
Monthly CP204 instalments are payable by the 15th of each month. Missed or late instalments attract a 10 percent late payment penalty under section 103(3), with a further 5 percent added after 60 days.
CP204A revision windows
CP204A revisions are allowed in three windows only: the 6th, 9th, and 11th months of the basis period. Use these windows seriously. A revision that brings your estimate closer to actual tax payable is the cheapest way to avoid the under-estimation surcharge. Form CP204B covers a change of financial year end.
CP204 is filed electronically through e-CP204 on MyTax using a digital certificate. Manual CP204 submissions are no longer accepted.

New 2026 rules: MITRS, and e-Invoice
Three 2026 changes are usually missed by deadline round-ups. Each one affects how you plan the rest of your calendar, so build them into your workflow early.
MITRS submission window
The Malaysian Income Tax Reporting System (MITRS) is the LHDN platform for submitting specified supporting documents under section 82B of the Income Tax Act 1967. Companies and LLPs must furnish MITRS documents on an electronic medium within 30 days after the Form C or Form PT submission due date. For a company with FYE 31 December 2025 filing Form C via e-Filing by 31 August 2026, MITRS documents are due by 30 September 2026. MITRS has been rolling out in stages from YA 2025 and is treated as a compliance requirement in its own right.
Mandatory e-Filing categories
Most return categories no longer accept manual submission. e-Filing, MyTax, MITRS, and e-WHT are the primary compliance channels for 2026.
On top of that, e-Invoice data increasingly cross-checks against Form C and CP204 figures. Reconciling your e-Invoices with your tax return before you file is now a basic quality-control step, not an optional nicety.
What happens if you miss a 2026 tax deadline?
Missing a deadline is rarely just a small admin mistake. It usually combines a late filing fine, a late payment penalty, and sometimes a CP204 under-estimation surcharge. Our LHDN penalty late tax filing article goes deeper, and the summary matrix below covers the five main exposures.
- Late filing of return (Form BE, B, C, PT, P): fine of RM200 to RM20,000, or imprisonment up to 6 months, or both, under section 112(1) of the Income Tax Act 1967. Section 120(1) applies to Form E and Form P equivalents.
- Late payment of tax: 10 percent of the outstanding balance after the due date under section 103(3). If still unpaid after 60 days, a further 5 percent applies, taking the total to 15 percent.
- CP204 under-estimation: 10 percent surcharge on the shortfall if the final tax exceeds the revised or original estimate by more than 30 percent, under section 107C(10).
- Form E late submission: separate action under section 120(1). Dormant companies are not exempt.
- Record-keeping: supporting documents must be kept for at least 7 years. Failure to produce records during an audit can trigger further penalties.

If your business has fallen behind on filings before, our companion guide on tax filing mistakes Malaysia SME walks through the fixes most small businesses need to make first.
Your month-by-month 2026 tax filing calendar
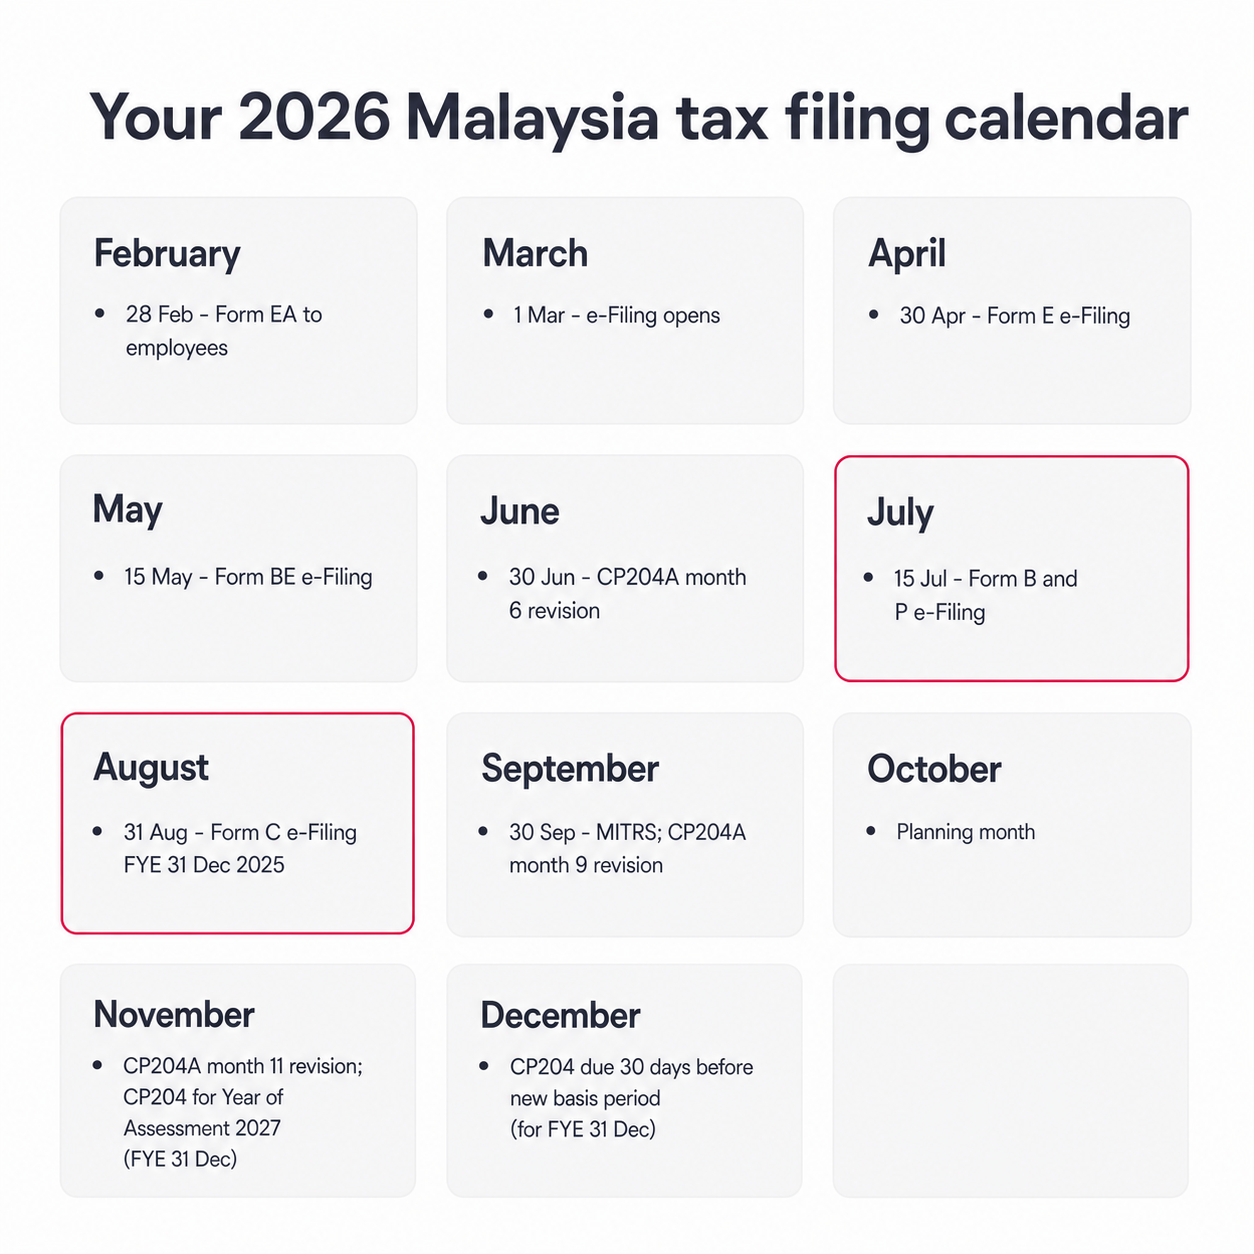
Use this calendar to plug every deadline into Google Calendar or your accounting software at the start of the year.
- February 2026. Issue Form EA to employees by 28 February.
- March 2026. LHDN e-Filing opens on 1 March for Year of Assessment 2025.
- April 2026. Form E e-Filing grace period closes on 30 April.
- May 2026. Form BE e-Filing grace period closes on 15 May.
- June 2026. For calendar-year companies, the first CP204A revision window opens in month 6.
- July 2026. Form B and Form P e-Filing grace period closes on 15 July.
- August 2026. Form C e-Filing grace period closes on 31 August for a company with FYE 31 December 2025.
- September 2026. MITRS documents due within 30 days after the Form C e-Filing due date. Second CP204A revision window opens in month 9 for calendar-year companies.
- November 2026. Third CP204A revision window in month 11. Submit CP204 for companies whose new basis period begins in December 2026.
- December 2026. Submit CP204 at least 30 days before a January 2027 basis period begins.
2026 Malaysia tax filing FAQ
When does e-Filing 2026 open?
LHDN e-Filing opens on 1 March 2026 for Year of Assessment 2025 through the MyTax portal.
When is Form C due for December year end?
If your financial year ends 31 December 2025, your Form C statutory deadline is 31 July 2026, with a grace period until 31 August 2026 for e-Filing. MITRS supporting documents under section 82B are then due 30 days after your Form C e-Filing date.
What is the penalty for late tax filing?
Late filing of Form BE, B, C, PT, E, or P carries a fine of RM200 to RM20,000, imprisonment up to six months, or both, under section 112(1) or section 120(1) of the Income Tax Act 1967. Late payment of tax attracts a 10 percent penalty under section 103(3), rising to a total of 15 percent if unpaid after 60 days.
Must dormant companies file Form E and Form C?
Yes. A dormant Sdn Bhd must still file Form E and Form C. Exemption is not automatic, and Form E is actionable under section 120(1) if not submitted on time.
When must a new Sdn Bhd file CP204?
A newly incorporated Sdn Bhd with a first basis period of at least six months must submit CP204 within three months from commencement of operations. If the first basis period is less than six months, CP204 is not required for that period, but Form C is still required.
Your 2026 tax filing readiness checklist
- Confirm your financial year end and map Form C and Form PT dates.
- Issue Form EA to all employees by 28 February 2026.
- File Form E via e-Filing by 30 April 2026.
- Submit or revise CP204 at least 30 days before your new basis period.
- Pay CP204 instalments by the 15th of every month.
- Plan CP204A revisions in months 6, 9, and 11 of your basis period.
- File Form C within 7 months of FYE, or 8 months via e-Filing.
- Prepare MITRS documents within 30 days after your Form C e-Filing date.
- Keep supporting documents on file for at least 7 years.
Speak to SSAM about your 2026 filing calendar
If your 2026 calendar is already looking tight, the earlier you plan, the cheaper compliance becomes. SSAM is a Ministry of Finance-licensed tax agent via TSE Taxation Services Sdn Bhd (registration 198401012049 / 124590-A), with 40 years of experience, 1,000+ loyal clients, and 99 percent client satisfaction. Our tax compliance and advisory team covers Form C, CP204, Form E, Form P, Form EA, personal tax, and closure of tax files, with accounting support starting from RM2,400 per year.
Speak to SSAM, WhatsApp the team on +6011-6529 9879, or email tax@ssam-group.com to lock in your 2026 filing calendar.
Primary data sources and references
- LHDN 2026 Return Form Filing Programme (PDF): https://www.hasil.gov.my/media/fqog1423/rf-filing-programme-for-2026.pdf
- LHDN Tax Estimation (CP204): https://www.hasil.gov.my/en/company/tax-estimation/
- LHDN MITRS Assessment Year 2026: https://www.hasil.gov.my/en/forms/filing-programme-for-documents-specified-under-section-82b-ita-1967-through-mitrs/assessment-year-2026/
- MyTax portal: https://mytax.hasil.gov.my/
- Income Tax Act 1967: sections 77, 77A, 82B, 103, 107C, 112, 120.
- PwC Malaysia, Important filing and furnishing dates: https://www.pwc.com/my/en/publications/mtb/important-filing-furnishing-dates.html
The information in this article is provided for general informational purposes only and does not constitute tax, accounting, financial or legal advice. Tax laws change frequently and may not apply to your situation. Always consult a qualified professional before acting on any information here.