Key Takeaways
- The LHDN email asking you to review your rental income tax position is a genuine notice, not a scam and not an audit letter, and the subject line wording can vary between batches.
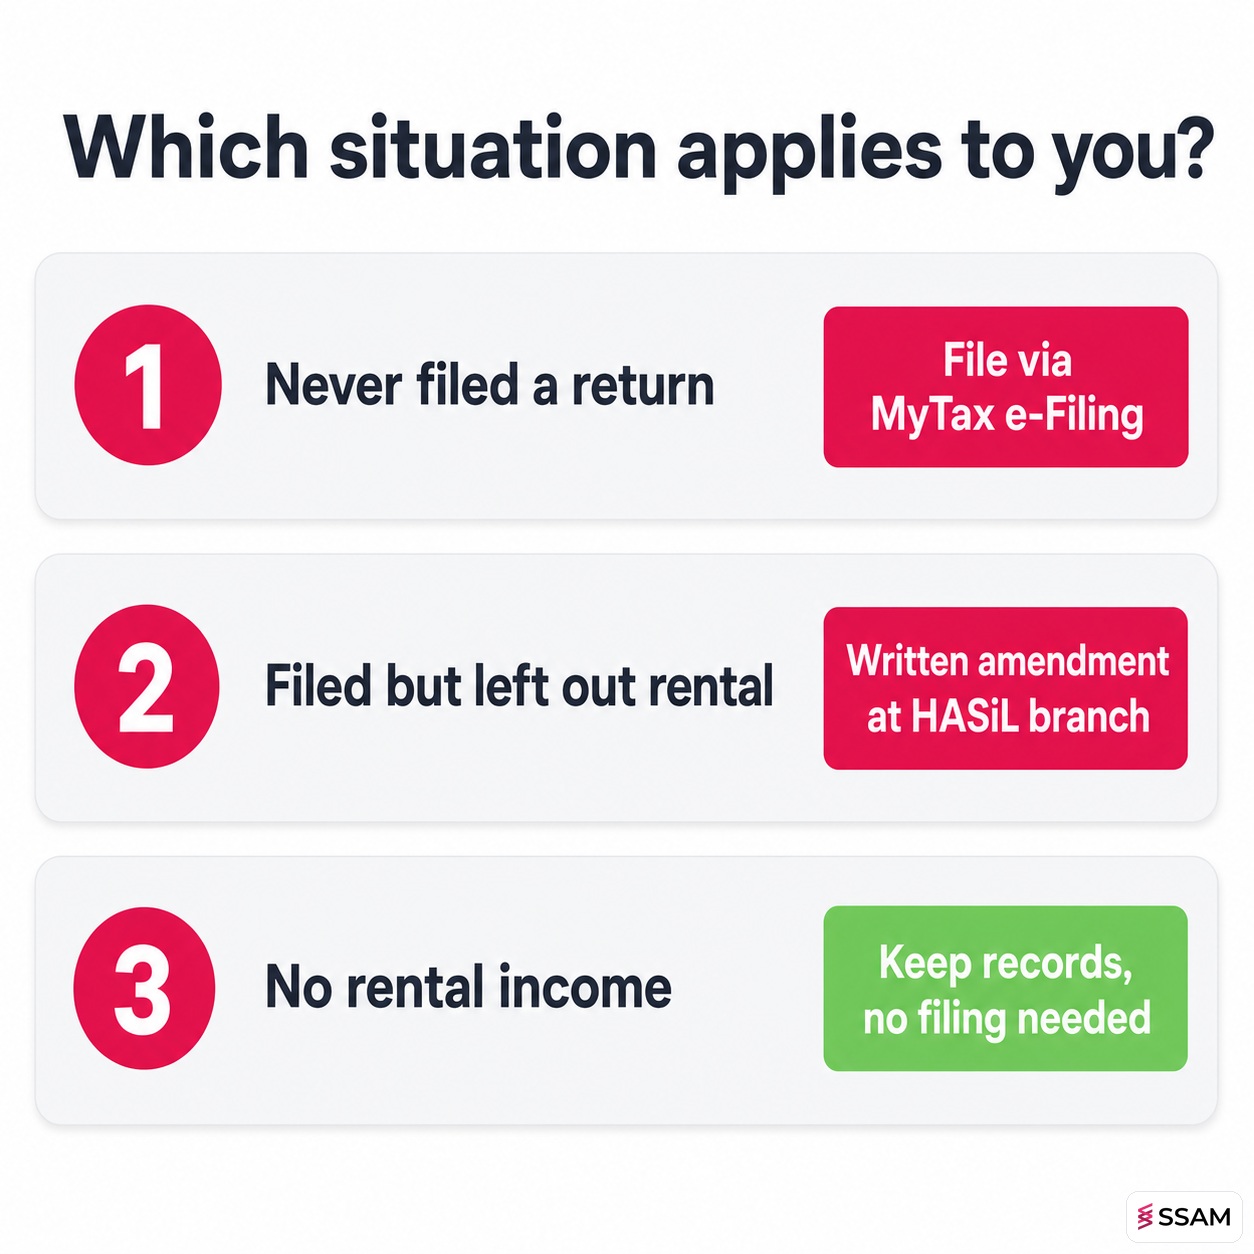
- LHDN sent it because its records show more than two premises under your name, and it wants any rental income reported by 31 July 2026.
- You have two routes: file through MyTax e-Filing if you never submitted a return, or send a written amendment to your HASiL branch if you filed but left rental out.
- Tax applies to net rent after allowable expenses, so gather your records before you panic about the gross figure.
- Acting before LHDN escalates is far cheaper than waiting for an audit.
If the LHDN rental income email about more than two premises is sitting in your inbox, take a breath, because you are not being singled out. Several of SSAM's own clients received the same notice recently, and recipients of this exact email have been asking what to do in Facebook groups, while creators on Instagram and Threads react to the same wave of LHDN rental income notices. The notice, which in the copies we have seen carries the subject “MESEJ PENTING: SILA SEMAK KEDUDUKAN PERCUKAIAN ANDA UNTUK TAHUN TAKSIRAN BERKAITAN”, is real, it is not an audit letter, and you still have time to put things right before 31 July 2026. This guide explains why you received it, what it actually says, and the exact steps to take, whether you have never filed a return, filed but left out rental income, or have nothing to declare at all. And if you would rather have a professional manage the response, SSAM's tax audit services in Kuala Lumpur cover exactly this kind of LHDN notice.
Is the LHDN rental income email genuine?
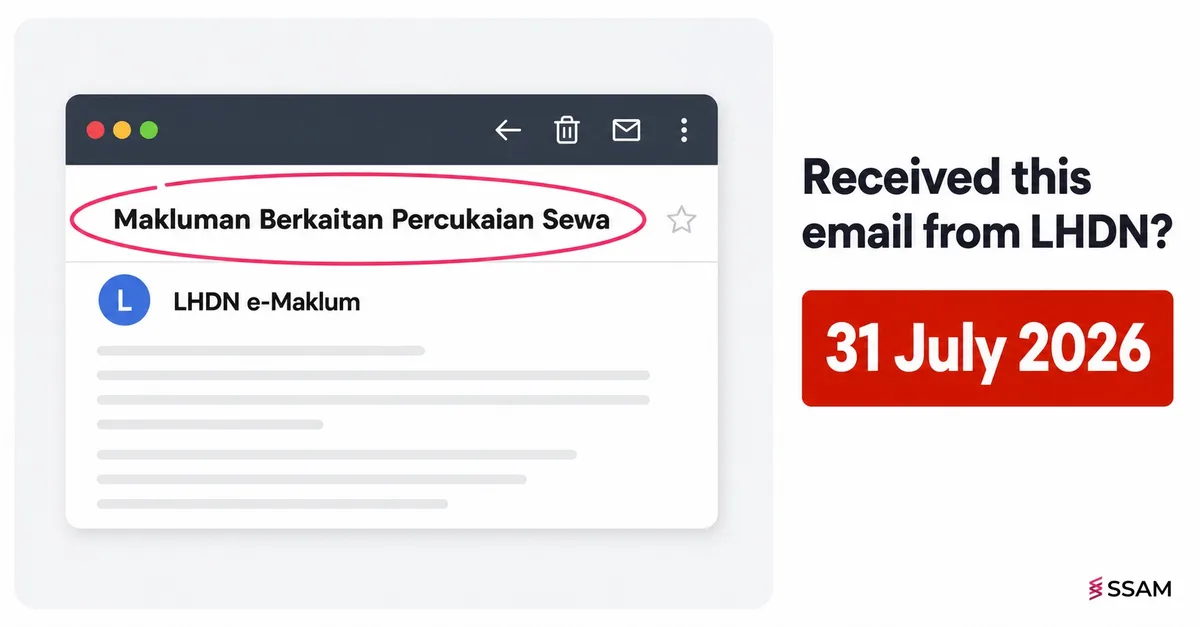
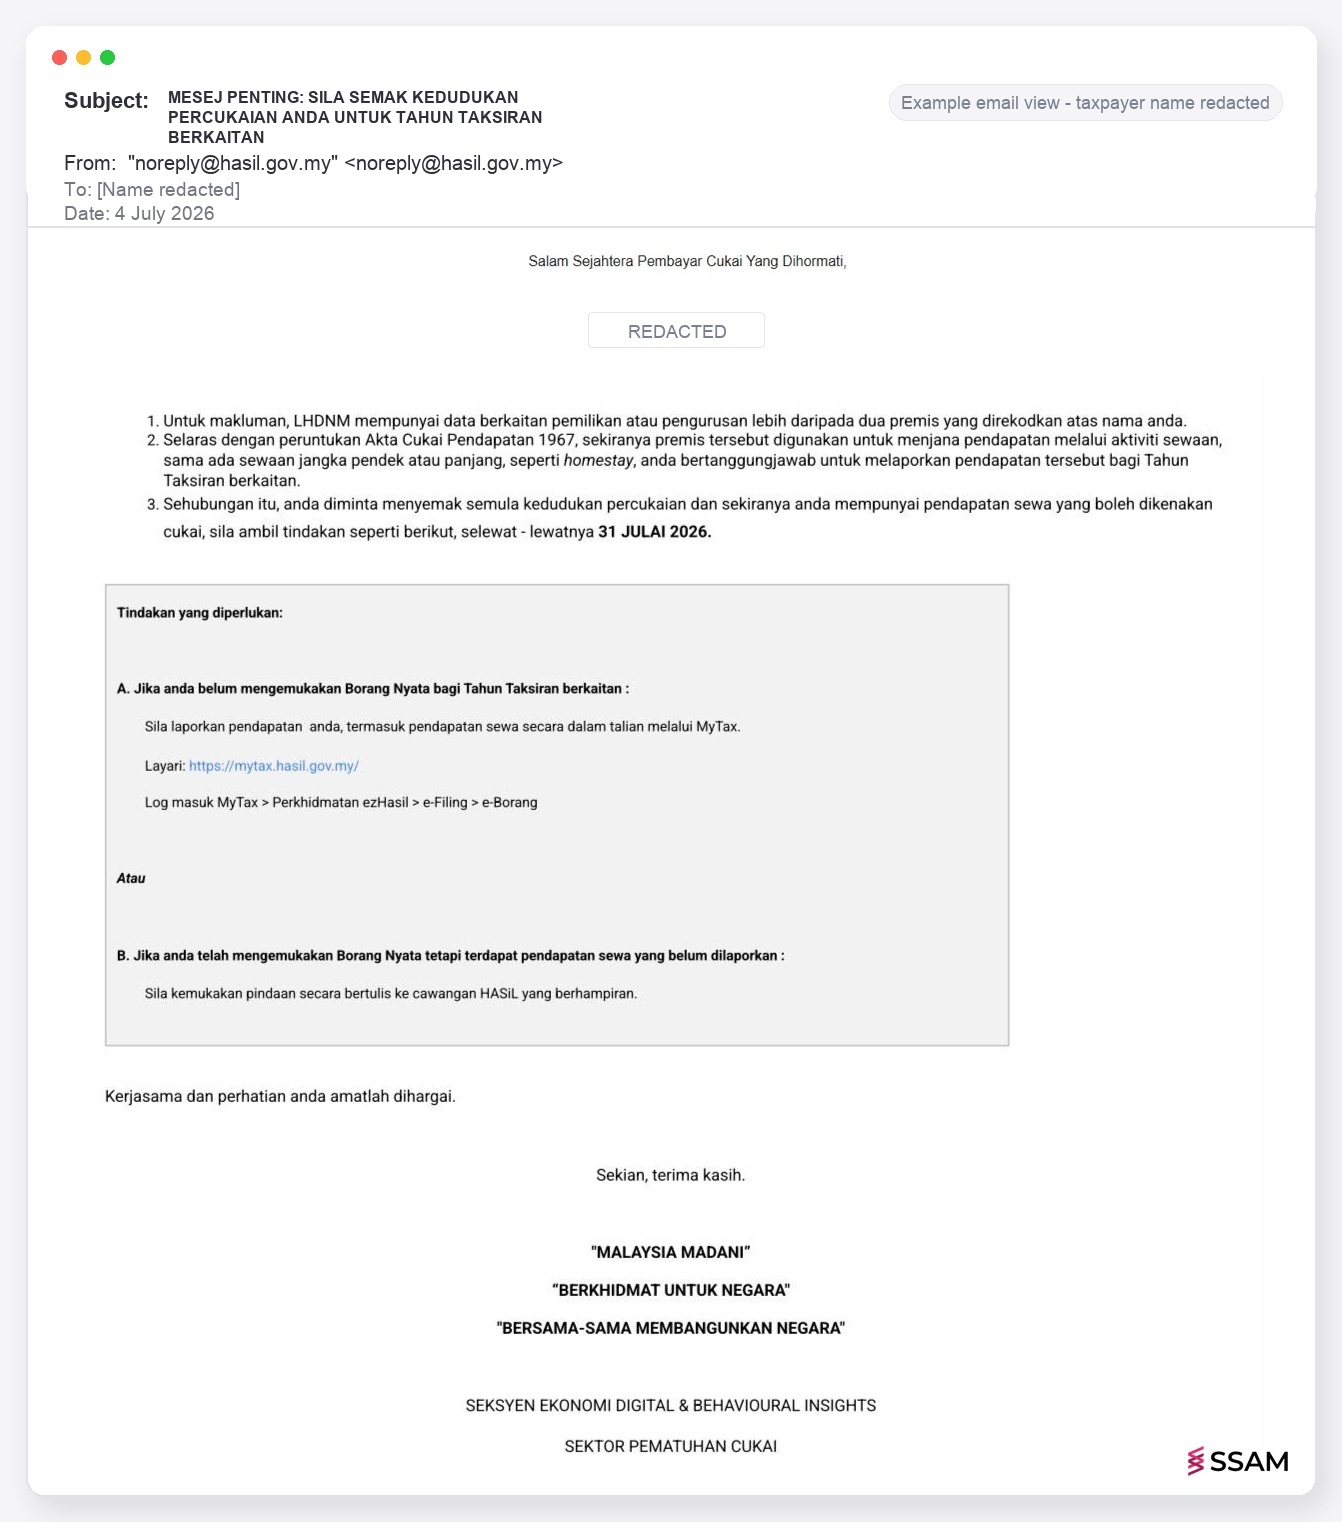
Yes. The email is a genuine notice sent by LHDN through its e-Maklum system from noreply@hasil.gov.my. The copies our clients received carry the subject “MESEJ PENTING: SILA SEMAK KEDUDUKAN PERCUKAIAN ANDA UNTUK TAHUN TAKSIRAN BERKAITAN”, though the wording is not always identical from batch to batch, and versions referring to “Makluman Berkaitan Percukaian Sewa” have also been reported. Do not dismiss a copy just because the title differs slightly. It was issued by the Seksyen Ekonomi Digital and Behavioural Insights under the Tax Compliance Sector, and it asks recipients to review and report rental income by 31 July 2026.
You are also far from alone in receiving it. The redacted example above is one of several notices shared with us by clients in recent days, and recipients of the same email are asking the same questions in public. In one Facebook group discussion, a recipient who just received the email asks what the first step should be, and the replies quote the letter's exact wording about more than two premises recorded under one name. Content creators on Instagram and Threads have been reacting to the same wave of LHDN emails about undeclared rental income. LHDN's data matching is doing exactly what it was built to do, and this campaign is part of it.
That said, always verify before you act on any tax email. Scammers copy official formats quickly, and a fake version of this notice may appear, possibly with a near-identical subject line. Since LHDN's own subject wording can vary between batches, the title alone proves nothing either way. The sender address is the better anchor. Check that it ends in @hasil.gov.my, confirm the email never asks for payment into a personal account, and log in to MyTax directly rather than through any link. You can also call the HASiL Contact Centre at 03-8911 1000. For the full verification process, use our checklist on how to tell whether an LHDN letter is genuine or a scam.
Why you received the email and what it asks
This notice is part of a new compliance approach. Instead of opening an investigation first, LHDN now nudges taxpayers to come forward on their own.
How LHDN knows about your premises
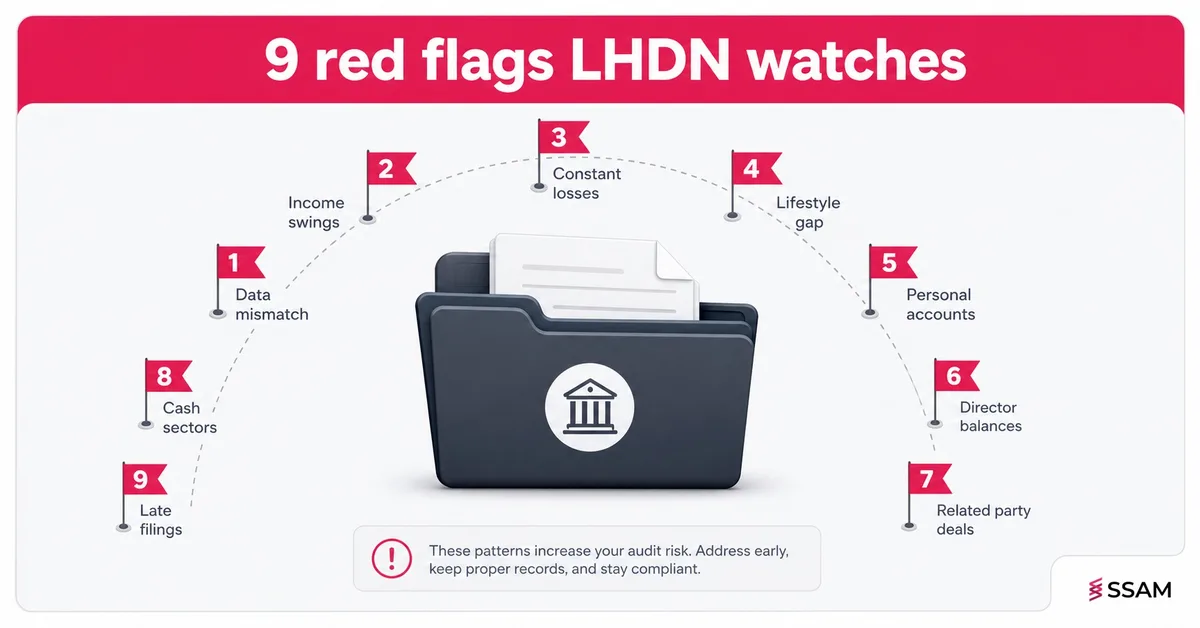
LHDN states in the email that its records show ownership or management of more than two premises under your name. That data comes from cross-checking property and tax records, and the unit behind the campaign, the Seksyen Ekonomi Digital and Behavioural Insights, exists specifically to encourage voluntary compliance through targeted reminders. In short, the email is a data-matching result, not an accusation. Unresolved mismatches are exactly the kind of red flag covered in our guide to LHDN tax audit triggers, so it pays to respond rather than ignore it.
The two actions the email requests
Under the Income Tax Act 1967, rental income from short or long term letting, including homestay, must be reported. The email then sets out two routes based on your filing history.
| Your situation | What the email asks you to do |
|---|---|
| You have not filed a return for the year involved | Report all income, including rental, through MyTax. Log in, then go to ezHasil, e-Filing and e-Borang |
| You filed a return but did not include rental income | Submit a written amendment with supporting documents to the HASiL branch that handles your tax file |
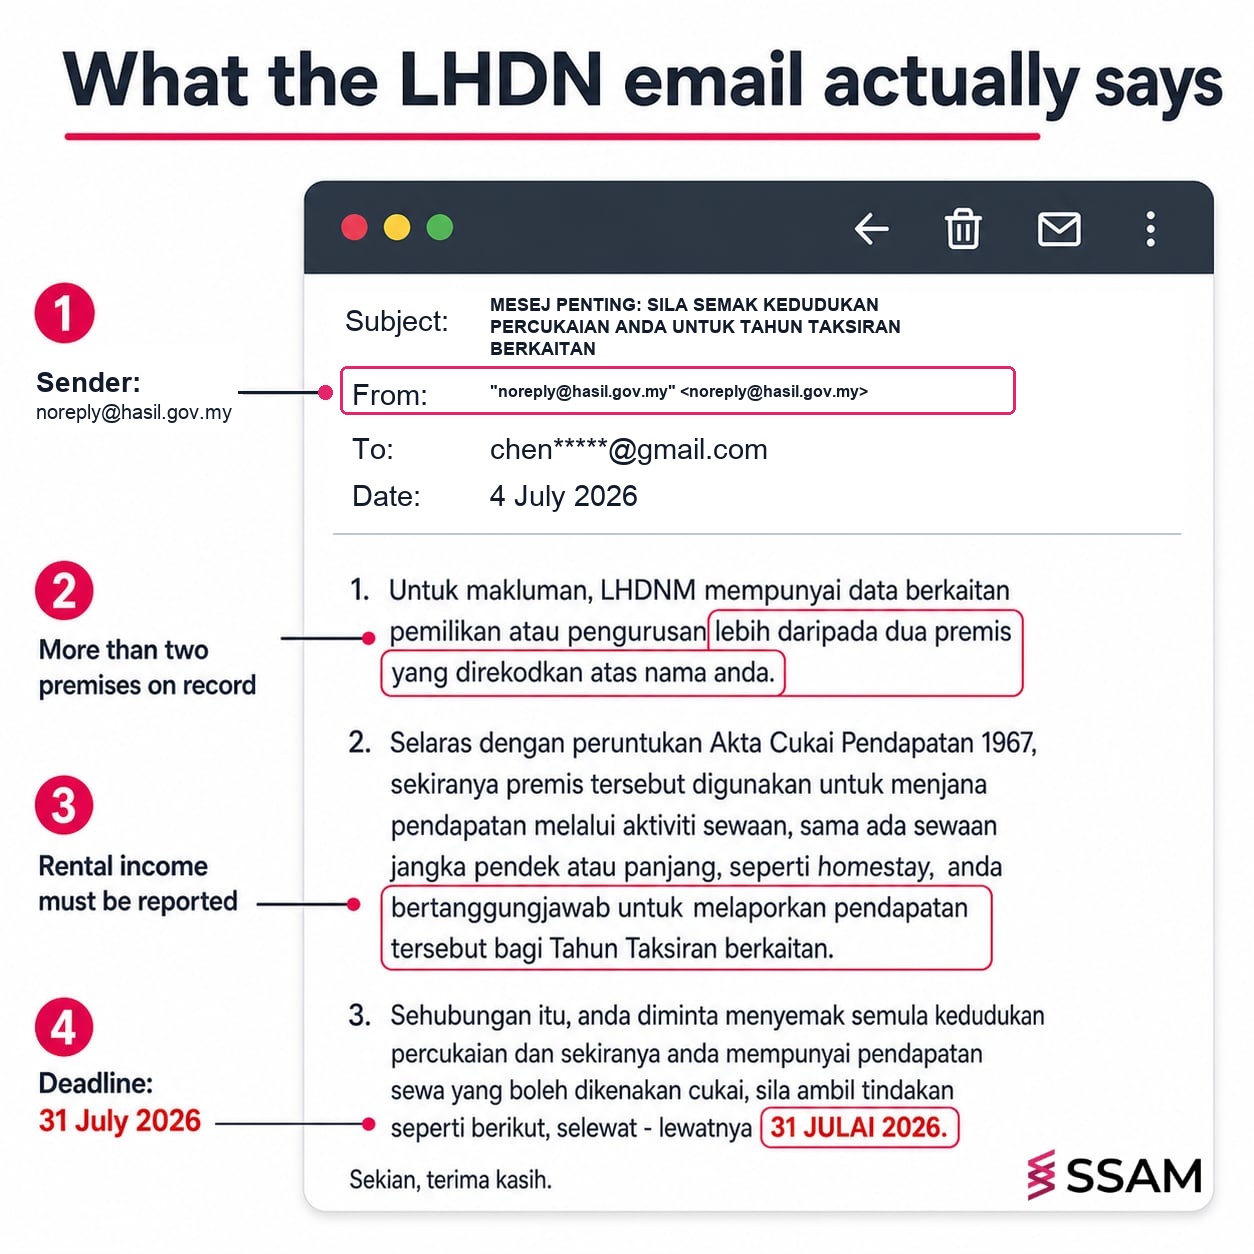
Which of these three situations applies to you?
Your next step depends entirely on your filing history, so place yourself in one of these three groups first.
You have never filed a tax return
Register for a Tax Identification Number through e-Daftar on MyTax if you do not have one, then file the return for the relevant year. Individuals without business income use Form BE, while those with business income use Form B. Declare your rental income under statutory income from rents together with your other income.
You filed but left out rental income
You cannot simply resubmit the form. Prepare a letter explaining the omission, attach supporting documents such as tenancy agreements and receipts, and submit the amendment to the HASiL branch that manages your file. Coming forward this way counts in your favour, because LHDN treats self-corrected returns far more gently than discrepancies it uncovers on its own.
Your premises earn no rental income
If your premises are vacant, owner occupied or used rent free by family, there is no rental income to declare and no filing action is required on this notice. Keep evidence all the same, such as assessment bills, utility bills showing your own occupation or the absence of tenancy agreements, so you can answer quickly if LHDN follows up.
How rental income tax is calculated in Malaysia
For most individual landlords, rent is taxed as non-business income under Section 4(d) of the Income Tax Act 1967, following the treatment set out in LHDN Public Ruling 12/2018. The key point is that you are taxed on net rent, not the gross amount your tenant pays.
A simple example. Say a condo brought in RM18,000 of rent for the year. You paid RM500 assessment tax, RM100 quit rent, RM6,000 housing loan interest, RM400 fire insurance and RM1,000 for repairs. Your taxable rental income is RM10,000, not RM18,000. That amount is added to your other income and taxed at your personal progressive rate.
Two more rules matter for this email. Joint owners each declare only their own share of the rent. And short term lets, including homestay and similar arrangements, must be reported too, since the notice names them specifically. The exact treatment of homestay income can vary with the services you provide, so confirm your position with a licensed tax agent if you are unsure.
Expenses you can and cannot deduct
Generally deductible against rental income: assessment tax, quit rent, housing loan interest, fire insurance premiums, repairs and upkeep, and property management or maintenance fees for the period the property was let.
Generally not deductible: one-off costs of securing the first tenant, such as agent commission, advertising, legal fees and stamp duty for the first tenancy agreement.
The real cost of ignoring the 31 July deadline
Doing nothing is the most expensive option on the table. The law sets out clear consequences, and the gap between coming forward and being caught is wide.
| Route | What it can cost |
|---|---|
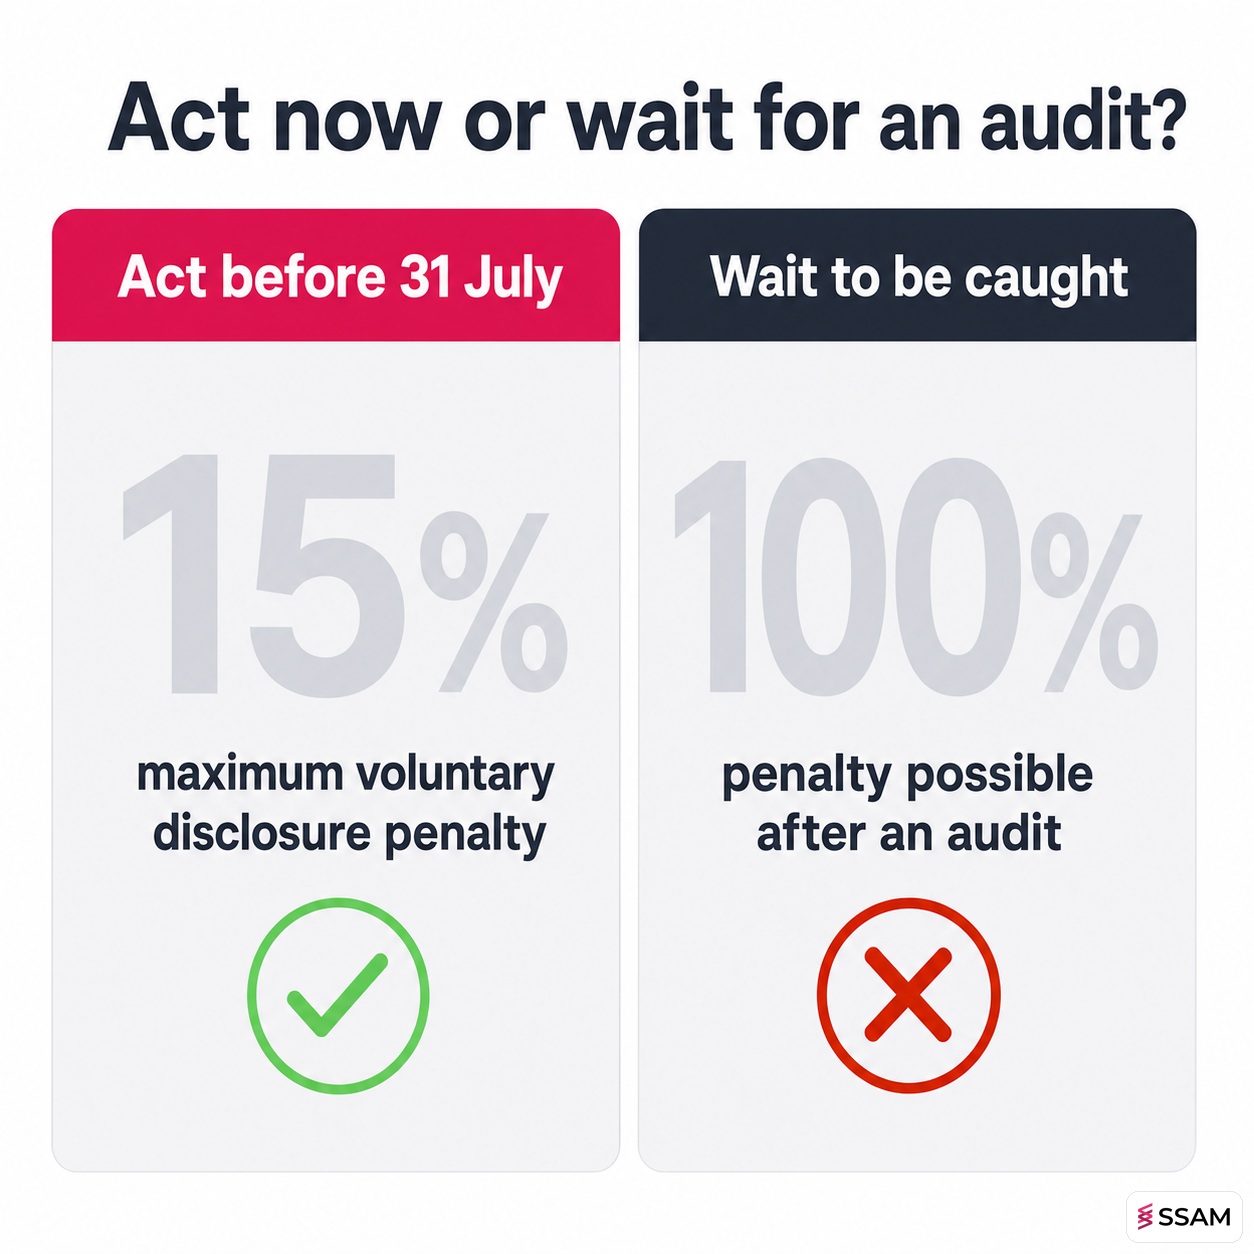
| Come forward voluntarily before enforcement | Penalty of around 10 to 15 percent of the tax undercharged, depending on timing |
| Wait for LHDN to uncover it in an audit | Penalty of up to 100 percent of the tax undercharged |
| Never file at all, Section 112(1) | Fine of RM200 to RM20,000, imprisonment of up to six months, or both |
| Incorrect return with prosecution, Section 113(1) | Fine of RM1,000 to RM10,000 plus a special penalty of double the tax undercharged |
The pattern is consistent: the earlier you act, the less you pay. Our guides to voluntary disclosure to LHDN and LHDN tax audit penalties walk through the numbers in detail. And if the data mismatch is never resolved, the matter can progress into a full review of the kind described in our complete guide to a tax audit in Malaysia.
How to respond before the deadline
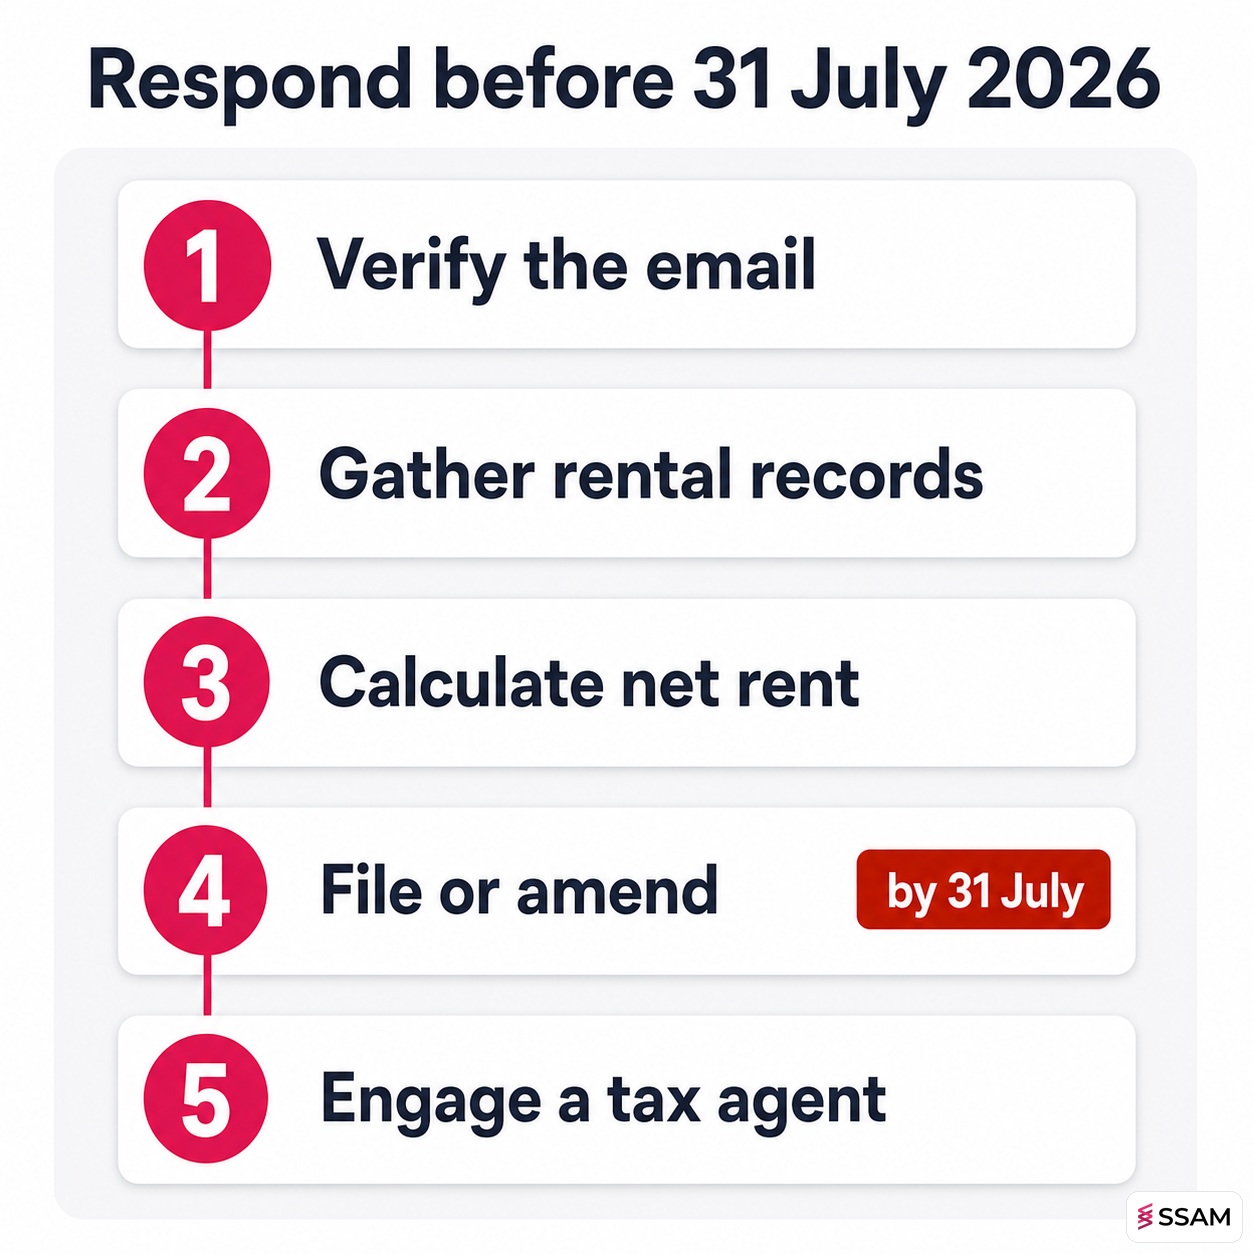
Here is the practical sequence to follow this month.
- Verify the email. Confirm the sender domain and, if in doubt, call HASiL at 03-8911 1000. Never click links in a message you have not verified.
- Gather your rental records. Tenancy agreements, rent received per property, assessment and quit rent bills, loan interest statements, insurance premiums, repair receipts and management fee statements.
- Work out net rent per property. Apply the deductible expenses above for each year of assessment involved.
- File or amend. No return filed: submit through MyTax under ezHasil, e-Filing and e-Borang. Return filed without rental: send your written amendment with documents to the HASiL branch handling your file.
- Get professional support if past years are involved. If several years of rental income were never reported, the order and framing of your disclosure affects the penalties you face. A licensed tax agent can manage that for you.
The decision logic is simple. Real email, real deadline, and a cheaper outcome the sooner you move. If you would rather not face LHDN alone, SSAM is a MOF licensed tax agent with 40 years of experience helping more than 1,000 businesses and property owners stay compliant. WhatsApp the team at +6011-6529 9879 and we will review your notice, compute your position and handle the filing or amendment before 31 July.
Frequently asked questions about the LHDN rental income email
Do I need to declare rental income if I make a loss?
If your allowable expenses exceed the rent for a property taxed under Section 4(d), there is no positive statutory income from that source and the loss generally cannot be set off against your other income. Keep the full computation and receipts, because the figures still need to stand up if LHDN asks how you arrived at them.
My premises are vacant or family stays there. Must I still respond?
No filing action is required if the premises generate no rental income. The email asks you to review your position, not to prove innocence. Keep evidence of vacancy or own use so a quick reply is possible if LHDN follows up on its data.
Do Airbnb and homestay earnings count as rental income?
Yes. The notice specifically mentions short term letting, including homestay. Depending on the level of services you provide, the income may be assessed as rental or as business income, which changes the form and the deductions available, so get advice if your operation is substantial.
How do joint owners declare rental income?
Each owner declares their own share of the net rent, following the ownership proportion. One sibling cannot declare the full amount on behalf of everyone. Each joint owner who received this email should review their own filing position separately.
Can I still act after 31 July 2026?
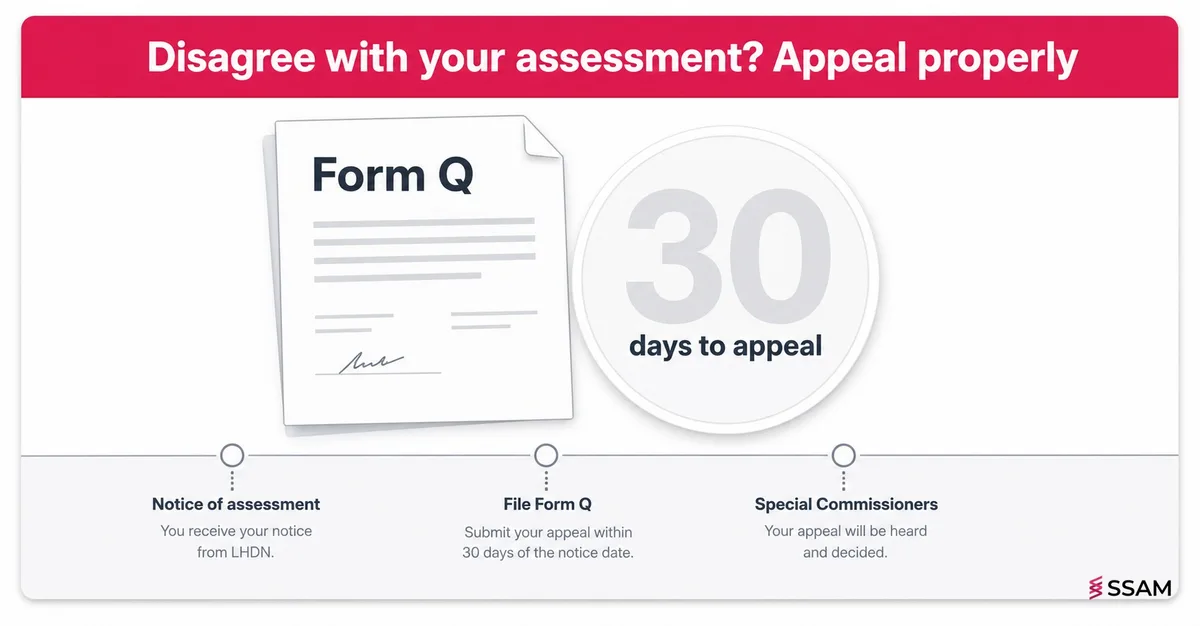
You can, and you should, but your position weakens. After the deadline passes, LHDN may move from a reminder to enforcement, and the matter can escalate into the processes explained in our comparison of a tax audit vs tax investigation. If an assessment is later raised and you disagree with it, you can still appeal an LHDN tax assessment within the allowed window. Acting late is still far better than not acting.
Data Sources / References
- LHDN, Offences, Fines and Penalties: https://www.hasil.gov.my/en/legislation/offences-fines-and-penalties/
- LHDN, Public Ruling No. 12/2018, Income from Letting of Real Property: https://phl.hasil.gov.my/pdf/pdfam/PR_12_2018.pdf
- LHDN, Pindaan Selepas Penghantaran Borang: https://www.hasil.gov.my/syarikat/pindaan-selepas-penghantaran-borang/
- MyTax portal: https://mytax.hasil.gov.my/
- EY Malaysia, Updated Tax Audit Frameworks: https://www.ey.com/en_my/technical/tax-alerts/updated-tax-audit-frameworks
The information in this article is provided for general informational purposes only and does not constitute tax, accounting, financial or legal advice. Tax laws change frequently and may not apply to your situation. Always consult a qualified professional before acting on any information here.